
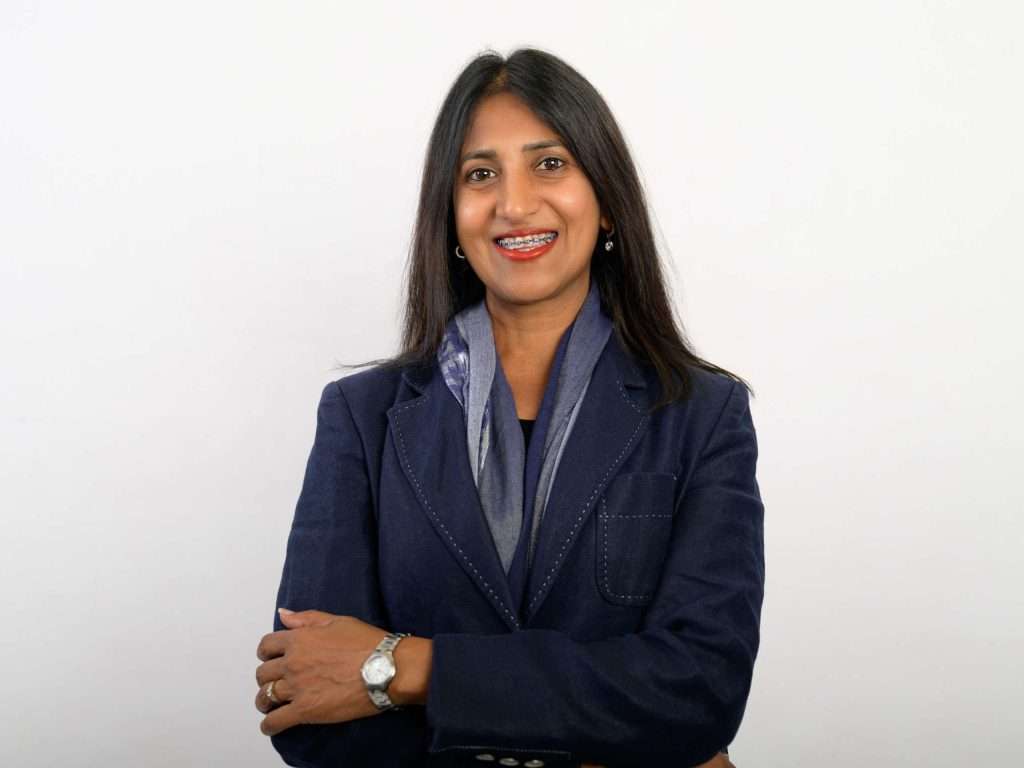
Avitha Nofal, executive of regulation, oversight and consumer awareness at the Ombud Council, discusses her career in financial sector regulation, the importance of consumer protection and the Council’s role in strengthening access to independent dispute resolution.
In an interview with CFO South Africa, Avitha Nofal, executive of regulation, oversight and consumer awareness at the Ombud Council, reflects on her career journey from legal practice to financial sector oversight. She discusses her leadership approach, the challenges facing South Africa’s financial ombud system and how effective regulation, collaboration and consumer awareness can improve access to fair and independent dispute resolution.
Take us back to the beginning of your career. What first drew you to regulation, and what experiences shaped your professional journey?
My professional journey began in the legal field. I qualified with a B.Proc degree and was admitted as an attorney. My first position was as a legal adviser at the Estate Agency Affairs Board, responsible for complaints against estate agents, mediation and prosecutions. At that stage, I probably didn’t fully appreciate how much that early experience would influence the direction of my career. It introduced me to the regulatory environment and gave me an understanding of the importance of protecting the interests of consumers, ensuring compliance and holding institutions accountable. I subsequently moved into private practice, working as a senior associate in the conveyancing department. This broadened my experience considerably, particularly in contracts, dispute resolution and conveyancing processes.
A defining move in my career was joining the Credit Ombud in May 2013. This brought together many aspects of my legal experience but, more importantly, allowed me to see the practical impact that financial disputes have on ordinary consumers. I became increasingly interested in the connection between regulation, consumer protection and access to dispute resolution. I realised that resolving individual disputes is important, but understanding why those disputes arise, identifying recurring problems and addressing the underlying conduct issues are just as significant. This experience shaped my transition into financial sector oversight. Regulation is not simply about rules being enforced, but as creating a financial industry in which institutions are accountable, consumers are treated fairly and there are independent, free and effective dispute resolution mechanisms when things go wrong for financial customers when disputes with financial institutions remain unresolved.
What has been the biggest turning point in your career, and how did it influence the leader you are today?
There were two turning points for me:
The first was moving from private legal practice into the Credit Ombud. It shifted my perspective from approaching disputes primarily from a legal standpoint to understanding the broader consumer protection implications of financial services. Working within the ombud environment taught me that resolving a dispute is not always just about determining who is legally right or wrong. It is also about ubuntu, fairness, accessibility, understanding the circumstances of the consumer and ensuring that dispute resolution processes are accessible, effective and impartial.
The second turning point was joining the Ombud Council in May 2024. This was a shift from being involved in the resolution of individual disputes to overseeing the broader financial sector ombud system. It required me to think more strategically about regulatory frameworks, systemic risks and the ongoing future reforms of the financial ombud system and dispute resolution in South Africa.
These experiences have influenced the leader I am today. I have learnt to consider the bigger picture and recognise that effective leadership requires both technical competence and the ability to bring people together around a common objective.
You serve as the Ombud Council’s second-in-command. How would you describe your leadership style, and what principles guide the way you lead?
I would describe my leadership style as inclusive, considered and outcomes driven. I believe in creating an environment where people understand their responsibilities, are trusted to deliver and feel comfortable contributing their perspectives. I value accountability, but I also recognise that people need the appropriate support, guidance and space to develop. I also believe that leadership is not about having all the answers. It is about asking the right questions, listening to different perspectives, challenging assumptions where necessary and making decisions based on evidence. It is important to distinguish between being busy and actually making progress. Another important principle is leading with integrity. In a regulatory environment, credibility is fundamental and I cannot expect the ombuds the Council oversees to demonstrate accountability, fairness and transparency if I do not apply those same principles within my organisation.
What has been your biggest professional challenge so far, and what did it teach you about yourself?
One of my biggest professional challenges has been navigating the transition from an established operational environment into a relatively new regulatory institution with a broader, more complex mandate. The Ombud Council has a unique responsibility. We are not an ombud scheme handling individual consumer complaints. We oversee the financial sector ombud system, monitor the performance of schemes, develop regulatory frameworks, identify systemic risks and facilitate greater coordination across the ombud schemes. This requires a different way of thinking and working. There is also the challenge of operating in an evolving regulatory environment, where policy developments, institutional reforms and changing consumer expectations require us to remain responsive while maintaining regulatory certainty. What this has taught me is the importance of adaptability, resilience and being comfortable with complexity and seeing these as opportunities to contribute to the financial sector ombud system reforms. I have also learnt that progress does not always happen as quickly as one would like. Sometimes it requires persistence, difficult conversations and the ability to maintain direction even when there are competing priorities. Significantly, for me, I have learnt that leadership involves being willing to step outside my comfort zone, taking responsibility while continuing to learn.
For someone unfamiliar with the Ombud Council, how would you explain its role in South Africa’s financial sector, and why is it important?
The Ombud Council is a statutory regulatory oversight body established under the Financial Sector Regulation Act. Our mandate is to assist in ensuring that financial customers have access to, and can use, affordable, effective, independent and fair alternative dispute-resolution processes when they have complaints about financial institutions.
An important distinction is that the Ombud Council is not itself an ombud scheme. We do not investigate or decide complaints between consumers and financial institutions, nor do we review or overturn decisions made by individual ombuds. Our role is to oversee and strengthen the financial sector ombud system. This includes monitoring the performance of schemes, setting regulatory requirements, protecting the independence of ombuds, promoting co-operation and co-ordination, addressing jurisdictional overlaps and improving public awareness and access. The Ombud Council’s role is particularly crucial because consumer protection does not end with regulating how financial institutions conduct themselves. There must also be an effective, independent and accessible mechanism available when consumers believe they have been treated unfairly. The financial system is only as strong as the confidence people have in it.
Access to effective redress is an important part of building that confidence.
The Council oversees both statutory and industry ombud schemes, including:
The statutory schemes include the Office of the Pension Funds Adjudicator (OPFA) and the Ombud for Financial Services Providers (FAIS Ombud).
Additionally, the Council oversees industry schemes such as the Johannesburg Stock Exchange Ombud (JSE Ombud) and the National Financial Ombud (NFO). The NFO was established on 1 March 2024 through the amalgamation of four previously recognized industry ombud schemes: the Credit Ombud, Ombudsman for Banking Services, Ombud for Long-term Insurance, and Ombud for Short-Term Insurance.
What does effective oversight look like in practice? How do you ensure that financial ombud schemes remain accountable while protecting their independence?
Effective oversight involves more than checking whether a scheme is complying with its rules. It requires us to understand how the scheme is functioning, whether it is delivering fair and timely outcomes, and whether its governance and operational arrangements support its independence. There are several important dimensions to this. First, we monitor performance and compliance, including how complaints are received, handled and resolved. Second, we consider governance, accountability and operational effectiveness. Consumers must be able to trust that their complaints are handled fairly and consistently. Third, we have a responsibility to protect the independence and impartiality of ombuds. Independence is fundamental to the credibility of the system and must be protected in both principle and practice. And finally, we look at the system as a whole. Where there are gaps, overlaps or inconsistencies between schemes, we must consider how these can be addressed so that consumers are not disadvantaged by the structure of the system.
What are the biggest challenges facing South Africa’s financial ombud system, and how is the Council working to address them?
Many consumers still do not know that independent financial ombud services exist, that these services are free to consumers, or which scheme they should approach. THE OMBUD COUNCIL, established by the Financial Sector Regulation Act, 2017, is mandated to assist in ensuring financial customers have access to and can use affordable, effective, independent and fair alternative dispute resolution processes for complaints about financial institutions. The Council works collaboratively with financial sector stakeholders, including the Financial Sector Conduct Authority (FSCA) and ombud schemes, to promote public awareness and education on the ombud system. Historically, South Africa’s financial ombud system consisted of several separate schemes, each with its own jurisdiction, processes and governing arrangements. This could make it difficult for consumers to identify the appropriate point of entry. The consolidation of four industry ombud schemes into the National Financial Ombud (NFO) in March 2024 was an important step towards simplifying the system.
Complaints information is an important source of intelligence regarding emerging consumer risks, recurring unfair outcomes, barriers to redress and potential systemic misconduct. Our oversight approach needs to evolve to identify and respond to these risks.
We need to ensure that consumers receive fair, efficient and consistent treatment across the different ombud schemes, while recognising that their mandates and the nature of their complaints differ. The Council is addressing these challenges through its regulatory and supervisory functions, the development of Ombud Council Rules, improved reporting frameworks, stakeholder coordination and the broader reform of the financial ombud system. Our overarching objective is to move towards a simpler, stronger and more accessible financial ombud system.
How do you identify patterns in complaints across different ombud schemes, and how can these insights help prevent similar problems from recurring?
At the Ombud Council, we have implemented a quarterly reporting framework which is then consolidated after analysing it for oversight and reporting purposes. This analysis supports regulators in responses conduct risks identified. Each complaint to an ombud scheme represents an individual consumer experience, but when we examine complaints collectively, they can reveal much broader patterns of conduct and potential consumer harm. Importantly, we do not simply look at which products attract the highest number of complaints. We also examine what is driving those complaints. For example, a complaint may relate to a particular financial product, but the underlying issue could involve inadequate disclosure, inappropriate advice, poor administration, unfair claims handling or failures in customer service. Once we identify a potential systemic issue, we consider whether it should be brought to the attention of the relevant regulator or other stakeholder. For example, if complaints reveal recurring problems relating to credit insurance, pension fund contributions or digital banking fraud, these insights can inform discussions with the relevant regulators about possible supervisory or policy interventions. Complaints data should not simply tell us what went wrong but rather it should help us understand why it went wrong and what needs to change to prevent it from happening again.