
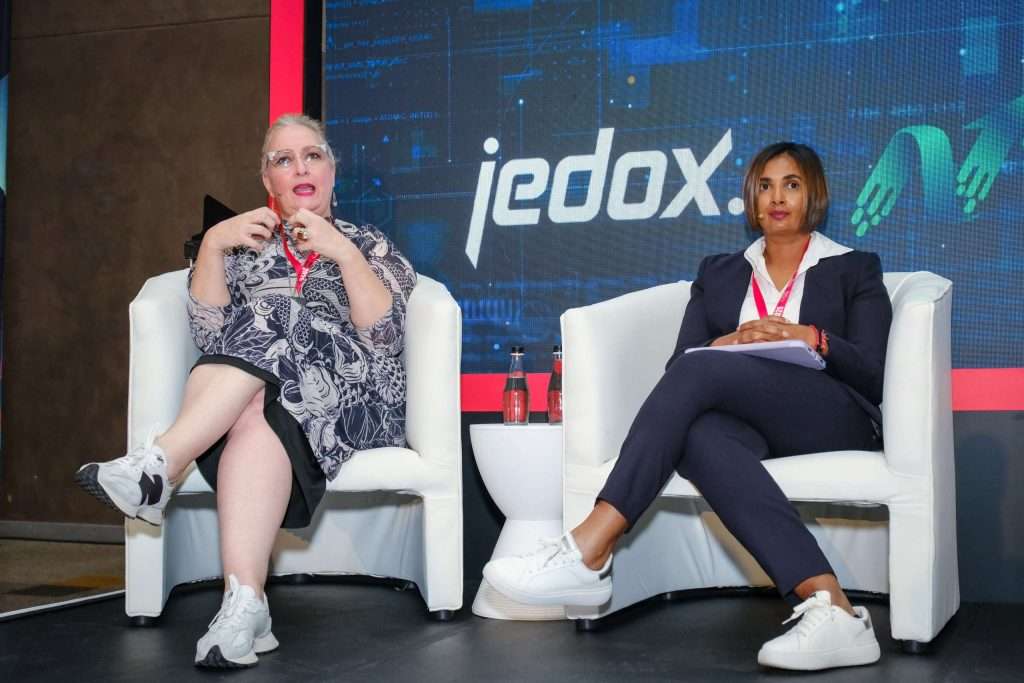
Finance leaders at the 2026 Finance Indaba were urged to move beyond annual ESG reporting by integrating sustainability data into financial systems, strengthening governance and improving forecasting as disclosure expectations evolve.
Environmental, social and governance (ESG) data is increasingly becoming a finance responsibility, with organisations needing to strengthen data governance, integrate sustainability measures into financial planning and prepare for more rigorous disclosure and assurance requirements.
Speaking during a session at the 2026 Finance Indaba on ESG data and financial decision-making, Yuraisha Moodley, director and founder of Nett Positive, outlined how developments in sustainability reporting, carbon taxation and investor expectations are changing the role of finance teams.
Mari Smuts, finance lead at iOCO Technology Group, said businesses needed to understand how ESG measures interact with operational and financial performance, rather than treating them as separate reporting requirements.
“The number can be right, but the full picture is still incomplete as individual metrics do not necessarily provide an accurate understanding of an organisation’s overall performance,” she said.
ESG data requires a connected approach
She said decisions made in one part of a business could have consequences across several functions, including finance, procurement, operations and sustainability.
“When procurement buys something from a different supplier, it impacts everyone,” she said, highlighting how decisions made in individual departments can affect environmental, social and governance outcomes across an organisation.
She warned that businesses risk losing sight of the overall picture when ESG information is divided between departments and consolidated through disconnected systems and spreadsheets.
Mari also referred to the Jevons paradox, which describes how improvements in efficiency can lead to increased overall resource consumption when the resulting efficiencies encourage greater use.
“You can reduce energy per unit and still increase your total energy use and that is why businesses need to consider absolute consumption alongside efficiency measures. Integrated data systems could help organisations connect carbon emissions with production volumes, costs, forecasts and the operational assumptions behind their performance,” she said.
Disclosure requirements are evolving
Yuraisha said sustainability reporting was moving towards more structured requirements, with governance, assurance and data quality becoming increasingly important for businesses.
She outlined the three ESG pillars, explaining that environmental considerations include carbon emissions, energy and water consumption, biodiversity and waste. Social measures cover workforce issues, health and safety, diversity, human rights and community impacts, while governance includes board independence, ethics, remuneration and risk oversight.
“ESG data is only as credible as the governance underneath it. I need to also highlight the importance of establishing responsibility for collecting, checking and approving sustainability information,” she said.
She also raised the concept of double materiality, which considers both how sustainability issues affect a company and how the company’s activities affect the world around it.
Yuraisha cited developments in international sustainability reporting standards and South Africa’s evolving regulatory environment as reasons for businesses to prepare their data and reporting processes ahead of requirements taking effect.
She said the International Sustainability Standards Board (ISSB) had been working towards a common baseline for sustainability and climate-related financial disclosures, while South African developments included the Financial Sector Conduct Authority's work on an ISSB adoption roadmap.
Yuraisha also referred to the launch of King V in October 2025 and said the King V Code applied to financial years beginning on or after 1 January 2026.
Sustainability increasingly affects financial performance
She said ESG considerations were becoming more relevant to finance through their influence on funding access, cost of capital, investor scrutiny and executive remuneration.
She highlighted the financial implications of carbon emissions, explaining that carbon costs and emissions forecasts could affect profit and loss projections, while climate-related factors could influence asset impairment testing, useful lives, provisions and going-concern assessments.
“Sustainability data is now being held at the same standard as financial data and this is pointing to the importance of controls, audit trails, formal sign-off and assurance,” she said.
She added that sustainability-linked loans and bonds could tie pricing to key performance indicators, making finance responsible for monitoring compliance with relevant commitments.
Yuraisha also warned that inconsistent methodologies, manual consolidation and limited audit trails could increase the risk of errors, restatements and unsupported sustainability claims.
She said weak data could undermine the disclosures intended to build investor confidence, making data governance an important part of managing conduct and reporting risks.
Building an assurance-ready reporting process
Yuraisha said businesses should establish an ongoing reporting system rather than assembling sustainability information only at the end of each reporting period.
She outlined four priorities: collecting data from a consistent source across business units, applying financial-style controls and validation processes, mapping information against multiple reporting frameworks, and monitoring performance through dashboards throughout the year.
She said a common data structure could support reporting against frameworks such as ISSB, the Global Reporting Initiative (GRI), Johannesburg Stock Exchange sustainability guidance and King V.
“Consistent reporting could reduce the administrative burden associated with annual ESG reporting while helping organisations prepare for assurance requirements. The cost of compiling ESG reports and obtaining assurance could be substantial, making it important to invest in processes and systems before reporting deadlines,” she said.
She concluded that businesses needed to establish reliable data foundations to support credible disclosures and more effective decision-making.
“Your data backbone makes every future reporting cycle faster, more credible, and gets you ready for assurance,” she said.